Buying a car is a major financial decision, and paying the full purchase price upfront isn’t always the most practical option. That’s where car financing can help. Instead of spending a large amount of money at once, you can spread the cost over several months or years through manageable repayments.
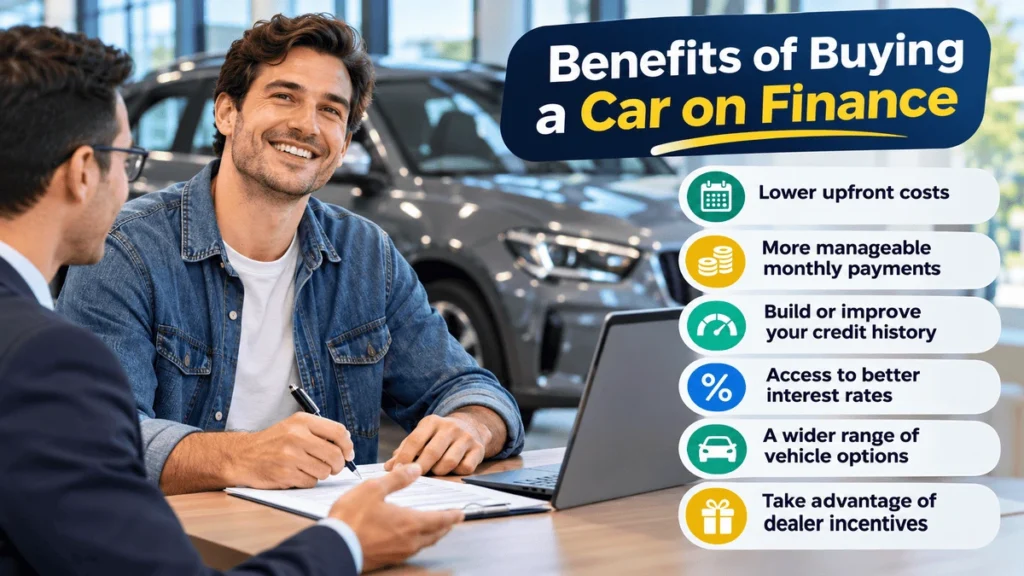
There are several benefits of buying a car on finance, including lower upfront costs, predictable monthly payments, access to a wider selection of vehicles, and the opportunity to build a positive credit history. Financing can also help you keep some of your savings available for emergencies and other important financial commitments.
However, taking out an auto loan is a financial commitment that deserves careful consideration. Interest rates, loan terms, credit scores, and additional fees can all affect how much you eventually pay.
Whether you’re considering a brand-new vehicle or a reliable used car, understanding how car financing works can help you make a more informed decision.
Let’s explore the main benefits of buying a car on finance and what you should consider before signing a loan agreement.
1. Lower Upfront Costs
One of the biggest benefits of buying a car on finance is that you don’t have to pay the entire purchase price immediately.
When purchasing a vehicle with cash, you need to have enough money available to cover the full cost. This can significantly reduce your savings and leave you with less financial flexibility.
With car financing, you generally make an initial down payment and borrow the remaining amount from a lender. You then repay the loan through regular installments over an agreed period.
For example, imagine you’re purchasing a vehicle worth $30,000. Instead of paying the entire amount upfront, you could make a $5,000 down payment and finance the remaining $25,000.
The actual monthly payment will depend on your interest rate, loan term, fees, and other financing conditions.
This approach allows you to purchase a vehicle without using most of your available savings at once.
Keeping some money available can be particularly useful for unexpected expenses, household bills, insurance payments, and other financial responsibilities.
However, remember that financing isn’t automatically cheaper than paying cash. You’ll generally pay interest and potentially other borrowing costs, so compare the total amount payable before making your decision.
2. More Manageable Monthly Payments
Another advantage of car financing is the ability to spread the purchase cost over a longer period.
Rather than making one substantial payment, you can divide the amount borrowed into regular monthly installments.
This can make it easier to organize your finances and plan your household budget.
For example, if you borrow $25,000, your monthly repayments will depend on the interest rate and repayment period. A shorter loan term generally means higher monthly payments but less interest paid overall. A longer term can reduce the monthly payment while increasing the total borrowing cost.
It’s important to find a repayment amount that comfortably fits your income and existing financial commitments.
Before agreeing to a loan, consider expenses such as:
- Monthly housing payments or rent.
- Electricity, water, and internet bills.
- Groceries and household expenses.
- Car insurance premiums.
- Fuel and regular vehicle maintenance.
- Emergency savings and other debt repayments.
Remember that an affordable monthly car payment doesn’t necessarily mean an affordable car.
A lender may approve you for a larger loan than you actually need. Choose a vehicle and repayment plan based on your financial situation rather than the maximum amount you’re allowed to borrow.
3. Opportunity to Build or Improve Your Credit History
Car financing can provide an opportunity to establish or strengthen your credit history.
When you take out an auto loan, your lender may report your account and payment activity to major credit reporting agencies. Making payments consistently and on time can help demonstrate responsible credit management.
This may be particularly beneficial for people who have a limited credit history and want to establish a record of successfully managing borrowed money.
A positive payment history can contribute to your overall credit profile, potentially helping you qualify for other financial products in the future.
However, it’s important to understand that financing a car doesn’t automatically improve your credit score.
Several factors influence credit scores, including payment history, outstanding debt, credit utilization, and the age and mix of credit accounts.
Missing payments, making late payments, or taking on more debt than you can comfortably manage can negatively affect your credit.
Before applying for an auto loan, review your credit report and understand your current financial position.
You can obtain free credit reports through AnnualCreditReport.com in the United States.
4. Access to Potentially Better Interest Rates
When financing a vehicle, the interest rate plays a major role in determining how much you’ll pay over the life of your loan.
Borrowers with stronger credit profiles may qualify for more competitive interest rates, although lenders also consider factors such as income, loan amount, vehicle age, down payment, and repayment term.
One of the best ways to find a suitable auto loan is to compare offers from different lenders before visiting a dealership.
Consider getting financing quotes from:
- Banks.
- Credit unions.
- Online auto lenders.
- Dealership financing departments.
- Other reputable financial institutions.
Pay particular attention to the annual percentage rate (APR). Unlike a basic interest rate, APR generally reflects the interest rate and certain borrowing costs, making it useful when comparing loan offers.
For example, two lenders might offer similar monthly payments but different APRs and repayment periods. Looking at the full loan details can help you identify which option is less expensive overall.
You should also consider getting pre-approved before shopping for a vehicle. This gives you an idea of the financing terms you may qualify for and provides a useful comparison when negotiating with a dealership.
The Consumer Financial Protection Bureau recommends comparing the APR, loan length, amount financed, and monthly payment rather than focusing on just one figure.
5. Greater Flexibility When Choosing a Vehicle
Financing can make a wider range of vehicles accessible because you don’t need to have the full purchase price available immediately.
Depending on your income, credit profile, down payment, and lender requirements, you may be able to consider vehicles that would otherwise be difficult to purchase with cash.
This could include newer models, family vehicles, fuel-efficient cars, or vehicles with modern safety and convenience features.
For example, someone who needs a dependable vehicle for daily commuting might consider financing a newer model rather than spending their entire savings on an older vehicle.
Newer vehicles may offer features such as:
- Advanced driver-assistance systems.
- Backup cameras and parking assistance.
- Improved fuel efficiency.
- Modern entertainment and navigation systems.
- Updated safety technology.
- Manufacturer warranty coverage, where applicable.
Of course, newer vehicles aren’t automatically more affordable to own. Insurance premiums, depreciation, taxes, maintenance, and financing costs should all be considered.
The best choice is a vehicle that meets your transportation needs without putting unnecessary pressure on your finances.
6. Opportunity to Take Advantage of Dealer Incentives
Another potential benefit of financing a vehicle is access to special offers provided by manufacturers and dealerships.
Car manufacturers sometimes offer promotional financing rates, cashback incentives, rebates, or other discounts to encourage customers to purchase particular models.
Depending on the offer, these incentives may reduce the overall purchase cost or make financing more attractive.
For example, a manufacturer might advertise a promotional APR for qualified buyers purchasing a specific new vehicle.
However, not everyone will qualify for these offers. Some promotions require excellent credit, a particular loan term, a specific model, or other conditions.
It’s also important to compare promotional financing with alternative offers.
A vehicle with a special low-interest financing deal might not necessarily be the cheapest option if another dealership offers a larger purchase discount.
Before accepting a dealer incentive, ask:
- What is the actual vehicle purchase price?
- What APR will I qualify for?
- How long does the promotional rate last?
- Is a down payment required?
- Are there eligibility restrictions?
- Is the incentive available alongside other discounts?
- What is the total amount I will repay?
Getting the answers in writing can help you avoid misunderstandings.
You can also improve your negotiating position by researching vehicle prices and comparing dealership offers. Our guide on negotiating prices at car dealerships explains how to approach the buying process more confidently.
7. Keep More of Your Savings Available
Using most of your savings to purchase a vehicle outright can leave you financially exposed if an unexpected expense arises.
For example, you might need money for medical bills, home repairs, family expenses, or an emergency.
Car financing allows you to spread the purchase cost over time, potentially leaving some of your savings untouched.
Having accessible savings can provide additional financial flexibility and reduce the need to rely on credit cards or other expensive borrowing options when something unexpected happens.
However, there’s an important consideration.
The money you keep in savings should be weighed against the interest and fees you’ll pay on the auto loan.
If your financing costs are high, paying cash or making a larger down payment could be more economical.
The right decision depends on your savings, financial priorities, loan conditions, and ability to manage regular repayments.
8. More Predictable Financial Planning
Fixed-rate auto loans generally come with predictable principal and interest payments throughout the agreed repayment period.
This can make household budgeting easier because you know how much you need to allocate toward your vehicle each month.
Instead of worrying about making a large payment all at once, you can plan your other financial commitments around a regular repayment schedule.
Predictability can be especially useful for people with consistent monthly incomes.
However, remember that your car payment isn’t the only expense associated with vehicle ownership.
Insurance, fuel, registration, maintenance, parking, and unexpected repairs can all affect your monthly transportation budget.
You should also check whether your financing agreement includes variable interest rates or other conditions that could change your payment obligations.
9. Opportunity to Own a Vehicle Without Leasing
It’s important to understand the difference between financing and leasing a vehicle.
When you purchase a car using a traditional auto loan, the lender generally holds a lien on the vehicle until the loan is repaid. You can usually use and maintain the car as its owner, subject to the loan agreement and applicable requirements.
Once the loan is fully paid, the lender’s lien can be released, giving you ownership without an outstanding auto loan.
Leasing works differently. You’re generally paying to use a vehicle for an agreed period rather than purchasing it through a traditional ownership loan.
Depending on the lease agreement, you may have mileage restrictions, wear-and-tear requirements, and additional charges when returning the vehicle.
For people who want to keep a car for several years, traditional financing may offer a clearer path toward full ownership.
It’s still important to compare the total costs of financing and leasing before deciding which arrangement makes more sense.
10. Greater Control Over Long-Term Vehicle Ownership
Financing a car can give you an opportunity to choose a vehicle that suits your longer-term transportation needs.
If you select a suitable loan and keep the vehicle after completing your repayments, you may eventually have several years of use without monthly loan payments.
This can provide additional flexibility in your future budget.
You may also be able to sell or trade in the vehicle when your circumstances change, although you’ll need to settle any outstanding loan balance and follow the lender’s requirements.
One important consideration is vehicle depreciation.
Cars generally lose value over time, and sometimes their market value falls faster than the remaining loan balance.
If you owe more than the vehicle is worth, you have what’s known as negative equity.
Making a reasonable down payment and choosing an appropriate repayment period can help reduce this risk.
Important Things to Consider Before Financing a Car
Although there are several benefits of buying a car on finance, borrowing money also creates financial responsibilities.
Before accepting an auto loan, take time to understand the following factors.
Interest Rates and APR
The interest rate directly affects how much you pay to borrow money.
Compare APRs from several lenders and check whether the quoted rate is fixed or variable.
A seemingly small difference in borrowing costs can make a noticeable difference over a multi-year repayment period.
Loan Repayment Period
The loan term determines how long you have to repay the borrowed amount.
Longer repayment periods can reduce monthly payments, but they generally increase the total interest paid.
Choose a repayment period that balances affordable monthly payments with reasonable overall borrowing costs.
Down Payment
A down payment reduces the amount you need to borrow.
For example, putting $6,000 down on a $30,000 vehicle means you only need to finance the remaining $24,000, before applicable taxes and fees.
A larger down payment may also reduce the risk of owing more than your car is worth.
Additional Fees and Optional Products
Some dealerships offer additional products such as extended warranties, service contracts, GAP insurance, and vehicle protection packages.
These products may be useful in certain circumstances, but they can also increase the amount you borrow.
Ask whether each product is optional, what it covers, and how much it costs.
Never agree to additional charges you don’t understand or want.
Total Cost of Ownership
Your monthly loan payment is only one part of owning a vehicle.
Before purchasing, calculate the expected costs of:
- Car insurance.
- Fuel or electricity.
- Routine servicing.
- Tires and replacement parts.
- Vehicle registration.
- Taxes and applicable fees.
- Unexpected repairs.
Considering these expenses will give you a more realistic picture of whether the vehicle is affordable.
How to Choose the Right Car Financing Option
Choosing the right financing arrangement requires more than finding a lender with an attractive monthly payment.
Start by determining how much you can comfortably afford without affecting your essential expenses and savings goals.
Next, check your credit profile and request loan quotes from multiple lenders. Compare the APR, loan duration, down payment, monthly installments, and total repayment amount.
It’s also worth obtaining pre-approval before visiting a dealership. This helps you understand your borrowing options and gives you a reference point when discussing financing terms.
When comparing dealership offers, negotiate the vehicle’s total purchase price separately from the financing arrangement.
Finally, read the entire agreement before signing. Make sure the written terms match what you discussed with the lender or dealership.
If anything is unclear, ask for an explanation before committing.
A little preparation can help you avoid unnecessary costs and choose a financing arrangement that fits your financial situation.
Frequently Asked Questions About Buying a Car on Finance
Is buying a car on finance a good idea?
Buying a car on finance can be a good option if you want to spread the purchase cost over time while keeping some of your savings available. However, it depends on the interest rate, loan terms, monthly repayments, and your overall financial situation. Always compare the total cost of financing with the cost of purchasing the vehicle outright.
Does financing a car help build your credit score?
Yes, an auto loan may help establish or strengthen your credit history when the lender reports your payments to credit reporting agencies. Consistently making payments on time can contribute positively to your credit profile. However, missed or late payments can damage your credit history.
Is it better to finance a car or pay cash?
Neither option is automatically better. Paying cash allows you to avoid loan interest and borrowing fees, while financing allows you to spread the cost and potentially preserve your savings. Compare the total financing costs with your financial needs and available cash before deciding.
What credit score do you need to finance a car?
There isn’t one universal credit score requirement for every auto loan. Lenders have different eligibility criteria, and approval may depend on your credit history, income, existing debt, down payment, and the vehicle you’re purchasing. Generally, stronger credit profiles can qualify for more competitive interest rates.
Can I finance a car with a low credit score?
It may be possible to obtain car financing with a lower credit score, but you could face higher interest rates, larger down payment requirements, or fewer loan options. Consider checking with banks and credit unions before accepting a high-cost dealership loan.
Is a longer car loan term better?
A longer loan term can reduce your monthly payment, making it easier to manage your budget. However, it usually increases the total interest paid and may leave you owing more than the vehicle’s market value for longer. Choose the shortest repayment period you can comfortably afford.
Can I pay off my car loan early?
Many auto loans allow early repayment, but the rules depend on the agreement and applicable law. Check whether your contract includes a prepayment penalty and whether additional payments are applied toward the principal balance. Paying off a loan early may reduce the interest you pay, depending on the loan’s interest structure.
Can I sell a car that is still under finance?
You may be able to sell a financed vehicle, but the outstanding loan generally needs to be settled as part of the transaction. Contact your lender to obtain the payoff amount and understand the process. If the car is worth less than the outstanding balance, you may need to pay the difference.
What is the difference between car financing and leasing?
Car financing generally involves borrowing money to purchase a vehicle, with the goal of owning it after repaying the loan. Leasing involves paying to use a vehicle for a specified period, usually subject to mileage and condition requirements. Some leases provide an option to purchase the vehicle at the end of the agreement.
Final Thoughts
There are several benefits of buying a car on finance, particularly for people who want to spread the purchase cost rather than use a large amount of their savings upfront.
From manageable monthly repayments and potential credit-building opportunities to access to newer vehicles and manufacturer incentives, financing can make purchasing a vehicle more flexible.
However, taking out an auto loan should never be a decision based solely on the monthly payment or the amount a lender is willing to approve.
Compare different lenders, review the APR, understand the repayment terms, and calculate the total cost of ownership before making a commitment.
Ultimately, the best car financing option is one that gives you the transportation you need while allowing you to maintain a healthy and manageable financial position.